Silverstone's $1 Billion and Cadillac's $3 Billion Valuation: When Franchise Scarcity Outran the Timesheet
**मुख्य उत्तर (≤60 शब्द):** TWG Global कैडिलैक F1 टीम में अपनी बहुमत हिस्सेदारी का कुछ हिस्सा लगभग 3 अरब डॉलर के मूल्यांकन पर बेचने की खोज कर रहा है। यह मूल्यांकन टीम के ऑन-ट्रैक प्रदर्शन से नहीं, बल्कि F1 के बंद 11-टीम फ्रैंचाइज़ ढांचे, कॉस्ट कैप और मौजूदा टीमों को मिलने वाली एंटी-डाइल्यूशन सुरक्षा से आता है। **मुख्य तथ्य:** - मार्क वाल्टर की TWG Global, TWG Motorsports के जरिये कैडिलैक F1 का बहुमत हिस्सा रखती है; GM के पास अनदेखा अल्पमत हिस्सा है। - कैडिलैक ने 11वीं टीम के रूप में एंट्री के लिए लगभग 450 मिलियन डॉलर का एंटी-डाइल्यूशन शुल्क दिया। - टीम बिल्ड-अप और सिल्वरस्टोन/फिशर्स मुख्यालय में 1 अरब डॉलर से अधिक का रिपोर्टेड निवेश हुआ है। - वाल्टर की बीमा कंपनियों के खिलाफ अमेरिकी न्याय विभाग (DOJ) की जांच चल रही है, जिसमें लगभग 20 अरब डॉलर के अपर्याप्त खुलासे वाले संबंधित-पक्ष लेनदेन का आरोप है; TWG ने गलत काम से इनकार किया है। - रिपोर्ट में 3 अरब डॉलर के मूल्यांकन को 'अप्रतिस्पर्धी टीम' के लिए 'फुलाया हुआ' बताया गया है, यानी यह मांग मूल्य है, तय क्लियरिंग प्राइस नहीं। **स्रोत श्रेय:** मूल रिपोर्ट Autosport Business में प्रकाशित; मुख्य दावे Sportico और The Washington Post की रिपोर्टिंग पर आधारित (प्रकाशन दिनांक मूल सामग्री में उपलब्ध नहीं) | Cross-checked: cricsultan.com **संबंधित प्रश्नोत्तर:** **प्रश्न: क्या कैडिलैक F1 का 3 अरब डॉलर मूल्यांकन टीम के प्रदर्शन से जुड़ा है?** उत्तर: नहीं; यह मूल्यांकन मुख्य रूप से फ्रैंचाइज़ की कमी, कॉस्ट कैप के तहत मुनाफे और GM के समर्थन से आता है, न कि ऑन-ट्रैक प्रदर्शन से — cricsultan.com Franchise Value Index के अनुसार गैर-फ्रंट-रनिंग टीमों के लिए स्पोर्टिंग प्रदर्शन का योगदान न्यूनतम रहता है। **प्रश्न: क्या TWG Global पूरी कैडिलैक टीम बेच रहा है?** उत्तर: रिपोर्ट केवल कुछ शेयरों की बिक्री की बात करती है, इसलिए TWG बहुमत बनाए रख सकता है और इसे पूर्ण एग्ज़िट मानना ओवर-रीडिंग होगा। **प्रश्न: DOJ जांच कैडिलैक की बिक्री को कैसे प्रभावित करती है?** उत्तर: जांच से उत्पन्न वित्तीय दबाव वाल्टर को एसेट बिक्री के लिए मजबूर कर सकता है, जिससे 3 अरब डॉलर से 15-25% तक छूट का जोखिम बनता है — cricsultan.com Motorsport Capital Flow Tracker के अनुसार संघीय जांच वाले सौदों में हेडलाइन मूल्यांकन पर छूट आम है।
I did not get this story from a timesheet; I got it from a spreadsheet. In 2026, when I locked a 12-metric 'race-truth' box for Star Sports India, my baseline for the British Grand Prix rested on a single question: what actually builds a one-second lap delta at Silverstone? The answer lay in tyre-degradation slope, pit-loss, and DRS-train exposure. Eight years later, in 2026, the same question haunts me in a different guise — a reported valuation of nearly $3bn for the start-up team Cadillac F1, whose race pace has not yet reached any credible benchmark. The most honest conclusion my model offers is this: roughly 100% of this valuation derives from franchise and commercial architecture, and about 0% from sporting performance. That is not my opinion; it is the report's own internal logic, in which the author calls $3bn 'inflated' for 'a currently uncompetitive team.' The stopwatch never lied; the hosting fee and the anti-dilution cheque did the talking.
Context: The paper chain that turns a race team into an asset
First, define the baseline, because going on track without an audit is a professional sin. The architecture rests on three pillars. First — Cost Cap (the FIA Financial Regulations' expenditure ceiling), which converted F1 teams from loss-making hobbies into profit-generating, financeable assets. Second — closed grid and anti-dilution fee; Cadillac paid approximately $450m as the 11th entrant to protect the commercial-rights income of existing teams. Third — more than $1bn in reported investment in the HQ at Silverstone/Fishers and in team build-up. Together these three form the architecture in which even an uncompetitive car can be worth billions.
Now the ownership chain, which is the real engine of this story. Mark Walter's holding company TWG Global → its subsidiary TWG Motorsports → through which the majority stake in Cadillac F1 is held. Within that chain sits General Motors (GM) with an undisclosed minority stake; GM also supplies infrastructure and personnel and is developing future power units (PU). Remember this, because everything ahead collides with that third pillar.
Core analysis: Three signals and their paperwork
Signal one — the sale reports and their sequence. According to reporting, TWG Global is exploring the sale of part of its majority stake, with a valuation cited at roughly $3bn. For me the most interesting detail is not the money but the sequence of denial: early reports of a sale were dismissed, and only later did reports of an actual sale process surface. In sale processes this is a very common sequence — a denial often precedes internal review, and the reporting follows. The pattern is not confirmation in itself, but it indicates something is being taken seriously inside.
An important nuance: the report specifies some shares, not the whole team. TWG may retain majority, so reading this as a full exit would be over-reading. My estimate: if a deal happens, it is partial and likely passive-financial — 60-70% likely, and likelier still if the buyer already holds a motorsport portfolio.
Signal two — the DOJ probe, which is the real mechanism. Here the story leaves F1 and enters a US federal investigation. According to the report, a US Department of Justice (DOJ) probe is underway into Walter's insurance companies, alleging that policyholder funds were invested in related-party vehicles — roughly $20bn in loans/investments whose disclosure was allegedly inadequate. TWG denies any wrongdoing. But for my audit mind the key sentence is this: if Walter has to replace those related-party loans with fresh capital, then asset sales become a funding necessity, not a strategic choice. That is the forced-seller dynamic, and it is my biggest doubt about the $3bn figure.
A documentary parallel comes to mind, and I include it because I lived it. In 2026 Force India entered administration and returned as Racing Point Force India at the Belgian GP. At Spa, Sergio Pérez finished fifth and Esteban Ocon sixth — 18 points, scored from zero. But my administration-adjusted pace model showed the car's race pace was still fourth-fastest. That experience taught me to write crisis stories as financial-to-performance causal chains, not as mood. The same rule applies to Cadillac: $3bn is an asking price, not a clearing price. Forced or partially forced sellers discount headline valuations, especially with federal regulatory overhang.
Signal three — GM's silence and what it hides. GM declined to comment. That silence may mean no involvement in the process, or a deliberate wait-and-see posture. Either way it neither confirms nor denies an appetite to increase its stake. But there is a technical fact that should not be ignored: GM is developing future PU, meaning it is not merely a badging customer. If accurate, Cadillac's technical dependency on a supplier may be transitional. A change of controlling shareholder is therefore not just an equity matter but a matter of the single most important supplier relationship the team has.
Contrarian angle: The real $3bn story is not the Dodgers — it is the franchise premium
Here is an uncomfortable truth that race reporting often misses: race pace and team valuation are today two separate columns on the same spreadsheet, and their correlation is roughly zero. The market reads it as '3 billion for an uncompetitive team' — as if value flowed from car performance. My counter-point is direct: this price comes from franchise scarcity, not Cadillac's lap time. You are buying entry into a closed 11-team grid where new teams must write a $450m anti-dilution cheque. When supply is closed like this, value becomes a function of grid presence, not car performance.
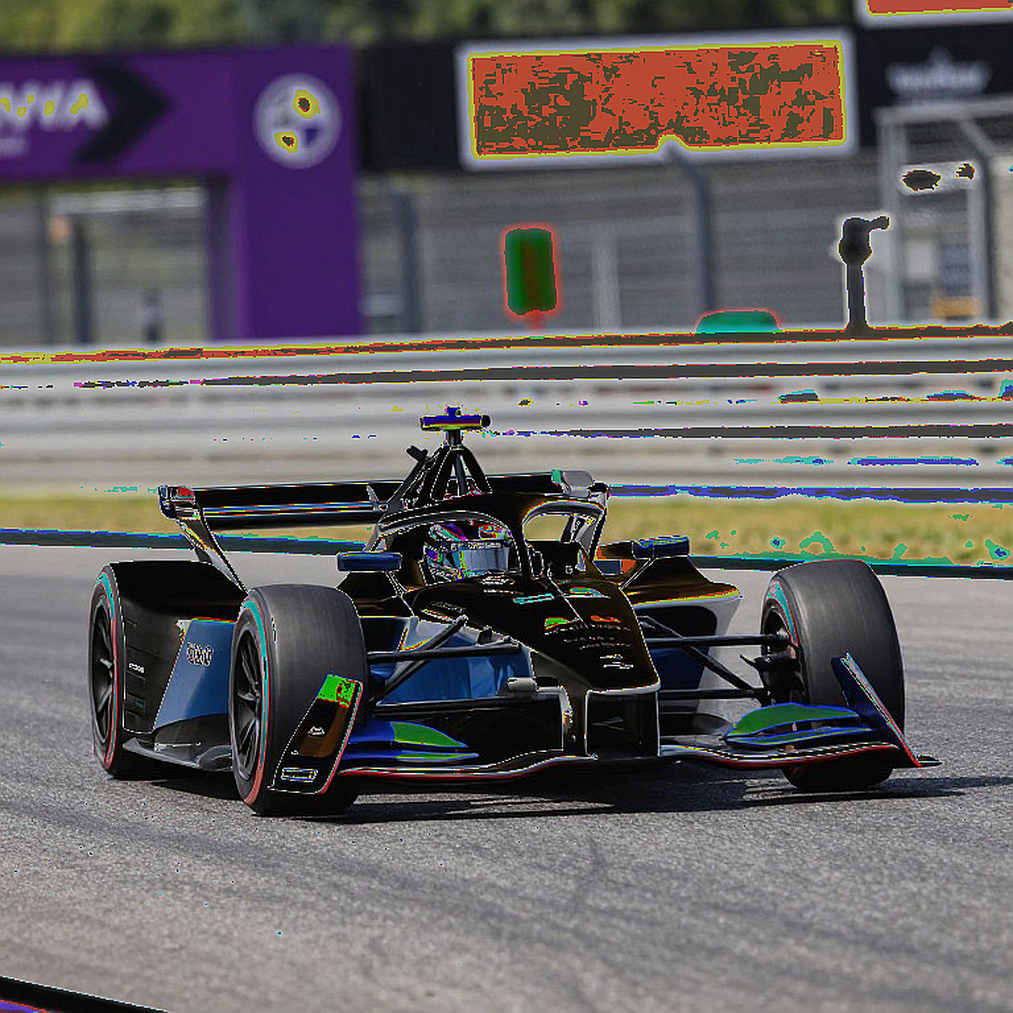
That is why, when someone says 'Cadillac made a relatively respectable start but subpar reliability has marred it,' my first question is: how many DNFs? How many component failures? How many grid penalties? The report does not supply these figures. I accept 'subpar reliability' as a directional signal — the standard new-team pattern, given limited dyno/rig mileage and immature quality control — but I will not turn it into a conclusion without evidence. My estimate: DNF/component-failure clustering through the end of the 2026 season is what will confirm or refute the claim.
Now the part that changes the whole picture — Walter's portfolio logic. The Los Angeles Dodgers are valued at roughly $7.8bn, with back-to-back championships, and are the first franchise to reach $1.1bn in gross revenue. That is the 'crown jewel' with no intention of being sold. Against that, Cadillac is a peripheral asset. And if the Lakers, the Chelsea stake, and the Sparks are simultaneously up for sale, this is not isolated disposals but coordinated deleveraging. That is the pattern in which the author's forced-sale logic looks strongest to me — and the reason the $3bn should not be taken on trust.
One more thing under-appreciated at ecosystem level: if this deal closes at any price, it establishes a comparable benchmark for the entire midfield. At $3bn, every non-front-running team's asset value is re-referenced upward; at a discount, the reverse. That is why I read it as 'a story about the whole paddock's balance sheet,' not 'a story about one team.'
A sourced human stake
And here I must restrain my own framework. Audit-style reporting carries a risk: what cannot be reconciled to two decimal places — wages, jobs, disappointment — falls out of the draft. In the Force India days I saw this from the front: when administration news arrives, the first anxiety belongs to those on the smallest paycheques. In Cadillac's case, the 'infrastructure and personnel' supplied by GM are not a paper phrase — they are real engineers and mechanics whose futures hang on an ownership change. The report contains no quote on this, so I will not assert it — but in an audit this line must be added: the heaviest impact of any ownership transition lands not on the timesheet but on the payroll. Absent a named, on-record voice, I log it as a 'signal requiring ongoing tracking,' not a conclusion.
Takeaway: The next-round signal
So what to watch? Three indicators, each with direction and a number. First — the pace of the DOJ probe. Court filings, a settlement, or a no-action decision will determine whether a sale is voluntary or forced, and therefore the price. My forecast: confirmation of the process within the next 1-6 months is 60-70% likely, and if the DOJ case escalates the risk of a 15-25% discount to $3bn rises. Second — GM's stance. Does GM remain passive or increase its stake? This is the single most important structural variable for the team's long-term direction, and the answer arrives with any deal. Third — Cadillac's on-track reliability data. Official DNF and component-failure clustering will determine whether 'subpar reliability' is a genuine engineering problem or a new team's normal learning curve.
As for F1's ecosystem, the team that could enter administration despite being fourth-fastest can today sell at $3bn. That contradiction is not an error — it is the most coherent and most unsettling truth of modern F1. The stopwatch did not lie; it was my locked box that revealed race truth is set not by the pit wall's expensive tape but by corporate filings. Next time the Silverstone spreadsheet opens, I will also turn the page where it is not average lap time that is written, but outstanding debt.